
Varoufakis Has Finally Found the Problem Bitcoin Solves
Yanis Varoufakis once called bitcoin a breathtaking solution to a problem we hadn't discovered yet. Now his movement DiEM25 has had its bank account frozen without explanation. Is bitcoin the answer to losing control over your own money?
 Contributed by
Erik
In a 2014 radio debate with Andreas Antonopoulos, Yanis Varoufakis called bitcoin “a breathtaking solution to a problem we haven't yet discovered”. Varoufakis is a left-wing economist (he calls himself an “erratic Marxist”) who rose to fame as Greece's outspoken finance minister during the euro crisis. With a touch of schadenfreude, the bitcoin community has noted that he has now found that problem. The trigger: news that the bank account of his movement, DiEM25, has been frozen by a Belgian bank.
🔴 URGENT: Our bank has cut us off from our own money.
— DiEM25 (@DiEM_25) November 3, 2026
Our bills haven’t stopped. Neither can our work. Help us build an emergency fund to keep DiEM25 going. Even €10 makes a difference.
Donate now: https://t.co/yAYtMqdO9A pic.twitter.com/NxJBcprtxr
This is the account that received the monthly contributions of tens of thousands of members and from which salaries and office rent were paid. Varoufakis went public with the case on X on 3 November. He described it as a closure “without explanation or warning” and hinted at a political motive.
The opposition comes from the left
It's striking that the fiercest opposition to bitcoin usually comes from the political left. In the US, the Democratic Party is the most hostile to crypto, and in the Netherlands, too, left-wing parties are the most sceptical. One reason is that the left places greater emphasis on consumer protection and wants to shield ‘the people’ from scams. Bitcoin's energy consumption doesn't help either. And yet. Isn't bitcoin the ultimate grassroots movement, ‘the people's money’? Shouldn't that appeal to the left? Apparently not, when push comes to shove: the left opts for state control over sovereign citizens.
A case like Varoufakis's is interesting. He's smart, has written extensively about bitcoin, and understands it better than most critics. So why the resistance? His recurring argument is that bitcoin is no solid foundation for alternative money. It's apolitical money, outside money. Yanis believes the monetary system should instead be reformed and democratised from within.
In his view, it should ultimately be possible to trust the central bank to backstop banks and protect the economy from depressions. He mainly takes aim at bitcoin maximalists, who envision a future for bitcoin as the global reserve currency, a variant of the good old gold standard. Varoufakis has issues with the gold standard and blames it for the Great Depression of the 1930s.
Rather than launching into a lengthy discourse on the role of hard money and credit in macroeconomics, we can narrow the discussion to a far more practical and pressing problem: situations can arise in which people can't access their money. Citizens simply don't have full control over the money in their bank accounts. A large part of Paraguay's population found that out last week too, when the central bank froze accounts at the country's fifth-largest bank.
“The irony is pretty obvious. Hopefully this prompts some introspection from Varoufakis about the nature of money in the digital age. He can disagree with bitcoin's monetary policy. He can maintain his objections to a fixed supply. But when a bank can shut off your access to money people voluntarily gave you, the ability to hold and transfer bitcoin without that bank's permission should be much harder to dismiss.”
Source: Marty Bent
What good is a democratically governed central bank if you can't get to your money? Varoufakis didn't see the problem then, and he probably does now.
It will be interesting to watch how interest in bitcoin evolves in an era of mounting cyberattacks on banks and payment systems - not to mention financial repression by governments.
More Alpha
Are you a Plus member? Then read on for the following topics:
- Blue wave sweeps America's ‘crypto capital’
- Blockchain exposes bank heist
- The crypto sector eyes American retirement savings
After that come the news snacks, a handy roundup of the news that really mattered last week.
1️⃣ Blue wave sweeps America's ‘crypto capital’
 Contributed by
Peter
Throughout 2025, Trump regularly took to the pulpit to hold forth in bold terms about his crypto policy. He was going to make the US the “crypto capital of the world”. A superpower in both the physical and the digital world.
JUST IN: 🇺🇸 President Trump says he's making the United States the "Bitcoin superpower, the crypto capital of the world and the undisputed leader in artificial intelligence." pic.twitter.com/C3i4gQ0oQ8
— Watcher.Guru (@WatcherGuru) November 5, 2025
In two years, Trump has set quite a lot in motion. A stablecoin law was passed, a strategic bitcoin reserve was established, a new wind began blowing through the key regulators, and the banks have gone from foe to friend of the industry; by now they're happily joining in themselves.
On the other hand, Trump failed to bring structure to the US crypto market. The bill meant to do just that, the Clarity Act, died just before the midterm elections. He largely has himself to thank for that: since returning to the White House, Trump and his sons have made at least $2.3 billion from crypto projects. A blatant display of self-enrichment that, understandably, stuck in the Democrats' craw.
It was hardly the only decision of Trump's that Americans found hard to swallow. Take the war against Iran, but also the rising cost of living, the trade war with neighbouring Canada and an excessive focus on monuments, data centres and AI.
And so the Republicans steered towards a painful defeat in the midterms. A drubbing they didn't see coming, judging by their first reflections. The party leadership was apparently stuck in a tunnel where the obvious was invisible. Trump had little choice but to somewhat resignedly congratulate the Democrats.
One of the things the data analysts on our side obsessed over was "composition"—whether the electorate looked close enough to 2024 for Republicans to win. And despite polls that showed a Democrat blowout, the data kept on telling us the same story: in some states turnout was…
— JD Vance (@JDVance) November 4, 2026
Either way, the Democrats now have a firm grip on both chambers. The million-dollar question is what this means for the US crypto sector, whose shifts, given its sheer size, are sometimes felt well beyond American borders.
At first, there was modest optimism. The regulators aren't changing, crypto has become an issue relevant to both camps, the sector has broadened beyond crypto companies alone with the participation of payment firms, banks and asset managers, and among the newly elected Democrats are enough pro-crypto candidates.
This constructive reading was helped along by financial markets that seemed to breathe ever more easily as the results became clearer. The bitcoin price recovered to above $80,000, and stock markets were flashing green as well. A Democratic victory would promise stability, a breath of fresh air compared with Trump's chaotic, erratic and aggressive policies.
But as time went on, the mood turned gloomier. Thursday's stock market crash acted as a catalyst. Almost all major stock indices tumbled. It was the worst second trading day after a midterm election in nearly a century of data.
The pessimism was fuelled by Democrats celebrating their win. They want to use their power to drag Trump into court and, of course, to push their political agenda: slowing the further development of AI, putting the brakes on data centre construction, and tightening oversight of the big tech companies that develop or run AI models.
Oversight Democrats are ready to take on the crooks, the con men, and the Trump crime family. Lawyer up. pic.twitter.com/Bat1pWfoEB
— Congressman Robert Garcia (@RepRobertGarcia) November 6, 2026
That policy outlook is the polar opposite of what the Republicans had promised the market, which was mainly about accelerating. AI is stealing the spotlight in many conversations, but that doesn't mean the landscape for the US crypto world stays the same.
The Republican version of the Clarity Act, for instance, has been declared dead for good, thanks, according to insiders, to the stance taken by the crypto industry itself. There's chatter in the corridors about a Democratic alternative to the Clarity Act, but that would be a bill with a heavier emphasis on anti-money laundering rules, consumer protection and ethics. We can only applaud the latter, but we're less keen on the risk of privacy and decentralised technologies coming under pressure.
On top of that, the Democrats will once again fill the key seats. The most important in this context is the chair of the banking committee. Everything to do with banks, stablecoins, digital assets, supervision of financial institutions and consumer protection in the financial sector passes through it. The likely chair? Elizabeth Warren, the woman who a few years ago led the charge against the crypto industry. Her comrade-in-arms Sherrod Brown is also getting his seat back on this committee, after being voted out in 2024 thanks to the millions lobby groups spent against him.
Sen. Elizabeth Warren is about to take the controls of the Senate Banking Committee, giving her the kind of expansive authority over the financial industry she has long sought https://t.co/RdTg3es7EN
— The Wall Street Journal (@WSJ) November 6, 2026
Some commentators believe the crypto sector has shot itself in the foot. Key opponents aren't just back, they're in even better positions than they held before the Trump era. “The levels of self-pwning here are 😑”, writes journalist Laura Shin.
The question is whether things will turn out as dire as they've been made to look in recent days. AI may well act as a lightning rod, and there's a good case to be made that the Democrats genuinely view the crypto sector differently than they did two years ago. Nor will the wind suddenly shift at the regulators, and Trump remains the man in the White House who has to sign bills into law for at least another two years.
Still, the midterms hangover has shifted, from ‘it's positive’ to a political climate that has changed in earnest. “Let's hope the next Congress can make productive, thoughtful policy a priority for the American people”, writes Galaxy's Alex Thorn, somewhat tentatively.
Fingers crossed!
2️⃣ Blockchain exposes bank heist
Contributed by Peter
Last week, hackers broke into a French bank and made off with 100 million euros. Who brought the case to light? An anonymous blockchain investigator, ZachXBT. His sleuthing led to Crédit Mutuel Arkéa, a mid-sized bank with more than 200 billion euros on its balance sheet.
French bank Credit Mutuel Arkea says €100 million missing after cyberattack https://t.co/u4FdNsAwVw
— Reuters (@Reuters) November 5, 2026
The story begins on Sunday 1 November. Large amounts of stablecoins are withdrawn from several exchanges, including Kraken and OKX. The funds are converted into ether, split across dozens of addresses and scattered over multiple blockchains. Some of it vanishes into Monero, a network designed to obscure transactions.
A day later, ZachXBT sounds the alarm. He claims that an as-yet unknown European entity has lost at least $106 million. On Tuesday, he raises his estimate to $133 million. And on Wednesday, he names the victim: Crédit Mutuel Arkéa.
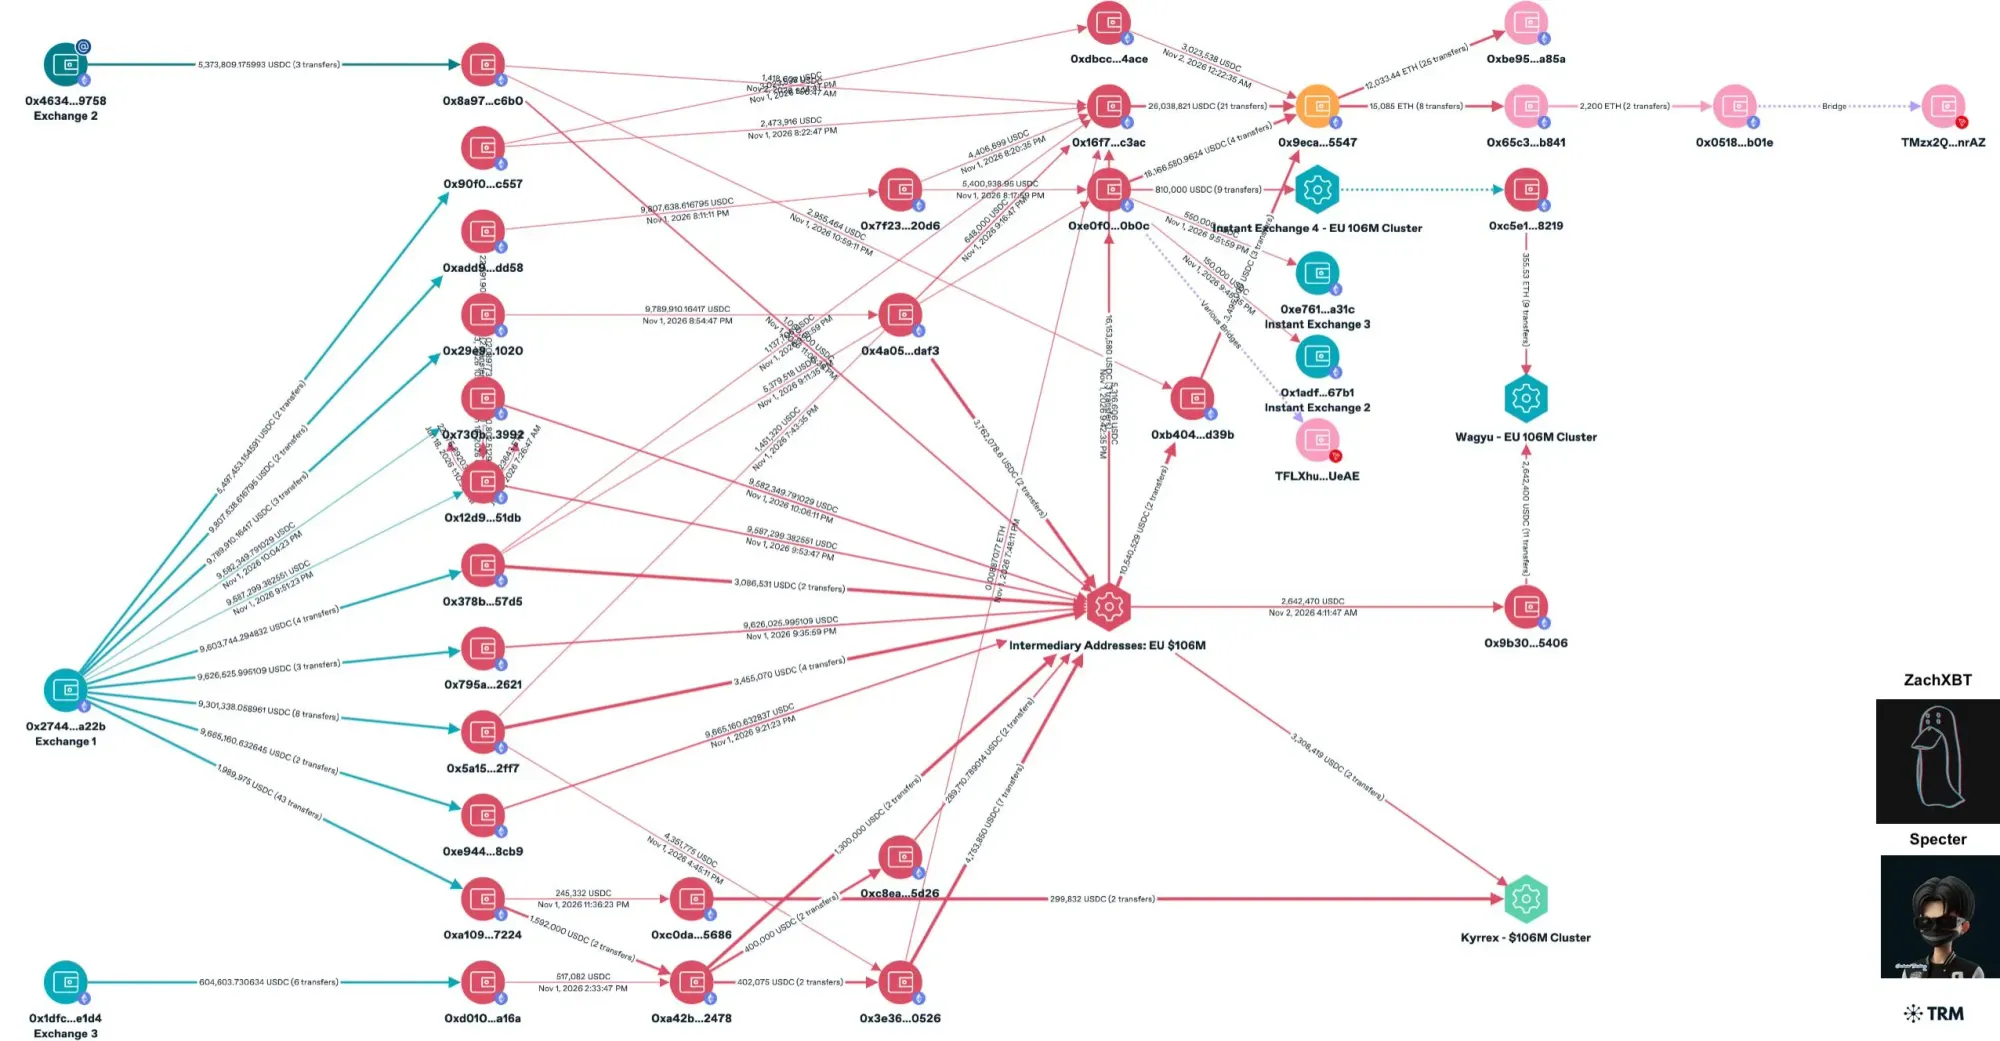
That same day, the bank confirms the heist. The perpetrators turn out to have gained access to the bank's infrastructure through a third-party service provider. They then transferred money from one of the bank's own accounts to other financial institutions. From there, funds were sent on to crypto exchanges. According to the bank, Arkéa customers' deposits were left untouched.
Relatively little is known about how the attackers managed to make the transfers, or how they were apparently able to convert such large sums into cryptocurrency through crypto firms with such ease. According to French newspaper Le Monde, the attack is virtually unprecedented in the European banking sector. Despite strict supervision and typically extensive security, the attackers managed to siphon off a sum roughly equal to a quarter's worth of Arkéa's net profit.
According to the bank, the suspicious activity was spotted quickly. Exactly when, it doesn't say. What is clear is that its public confirmation only came after ZachXBT had revealed its name. Arkéa also states that no human error was involved; “it was a sophisticated attack”.
Blockchain networks play a dual role in this story.
On the one hand, they bring transparency to a process that might otherwise have gone unnoticed. An independent investigator was able to trace suspicious fund flows, reconstruct the scale of the fraud and identify the victim, all without access to internal data.
On the other hand, they're the highways the thieves used to make their getaway with the loot. The crypto firms that exchanged the stolen euros will no doubt be fielding some awkward questions about that for a while yet.
3️⃣ The crypto sector eyes American retirement savings
Contributed by Peter
The US government wants to make it easier to save for retirement through employer plans with investments in crypto. To that end, the Department of Labor has submitted a rule to the White House for review, the final text of which has not yet been made public.
Alongside their public Social Security benefits, many Americans save for retirement through a so-called 401(k). They invest part of their salary in it, often topped up by their employer. With the traditional version, they only pay income tax when they withdraw the money. How much they end up with depends on their contributions and investment returns.
Employees choose from an investment menu put together on behalf of their employer. It typically includes equity and bond funds. There are also funds that adjust the investment mix as the retirement date approaches. Crypto is sometimes available, but still plays only a minor role.
That's partly because employers and plan administrators are held responsible for offering a ‘prudently’ assembled lineup. With cryptocurrencies, that means grappling with issues such as their sometimes hefty volatility and how they're held in custody. Under President Biden, the department explicitly warned against crypto investments in retirement plans. It withdrew that warning last year.
With the new rule, the government aims to give plan administrators more legal certainty when offering investments, including crypto and private equity. If it's approved, that doesn't mean employers will be required to add crypto to the mix.
For the crypto sector, the stakes are high. At the end of June, $10.8 trillion was held in US 401(k) plans. If just one percent of that went into crypto, it would amount to $108 billion.
🍟 Snacks
To wrap up, a few quick snacks:
- According to Tether, the number of its gold tokens has grown by almost 60 percent this year. That growth stands out, because the gold price has actually fallen since its peak in early January. Tether says this proves what kind of buyers the tokens attract: long-term investors with deep conviction in gold's role in the financial system. As backing, Tether now holds almost 26 tonnes of gold in a Swiss vault. The purity of the stored gold is tested every quarter, and the test results are available for anyone to view.
- Bitcoin miner Riot is selling its bitcoin holdings to build AI data centres. In the first nine months of this year, the company sold 20,264 bitcoin for almost $1.5 billion. At the end of September, Riot had 2,418 BTC left. Rival Core Scientific announced last week that it will wind down its mining operations from 2027. For the bitcoin market, selling pressure from this corner is steadily easing: the miners' pivot to AI is in its final stages.
- ICE, the parent company of the New York Stock Exchange, wants to open up the US market to Hyperliquid. To do so, it plans to team up with trading platform trade[XYZ]. The partnership centres on perpetual futures, or perps for short: contracts with no expiry date that let investors trade the prices of stocks, commodities and cryptocurrencies around the clock. ICE is also investing in trade[XYZ] and aims to act as operator of the regulated markets on offer. The plans still need regulatory approval.
- The US scraps its plan to require personal data sharing for smaller international transfers. FinCEN and the Federal Reserve wanted to lower the threshold from $3,000 to $250, but are now withdrawing that proposal. Under the so-called Travel Rule, financial institutions must pass customer data on to the next institution in the payment chain. The threshold remains $3,000, including for crypto transactions covered by the rule. The agencies consider the 2020 proposal outdated given changes in the crypto market.
Thank you for reading!
To stay informed about the latest market developments and insights, follow our team members on X:
- Bart Mol (@Bart_Mol)
- Peter Slagter (@pesla)
- Bert Slagter (@bslagter)
- Mike Lelieveld (@mlelieveld)
We appreciate your continued support and look forward to bringing you more comprehensive analysis in our next edition.
Until then!